Fake Organics

January 17, 2018

January 17, 2018


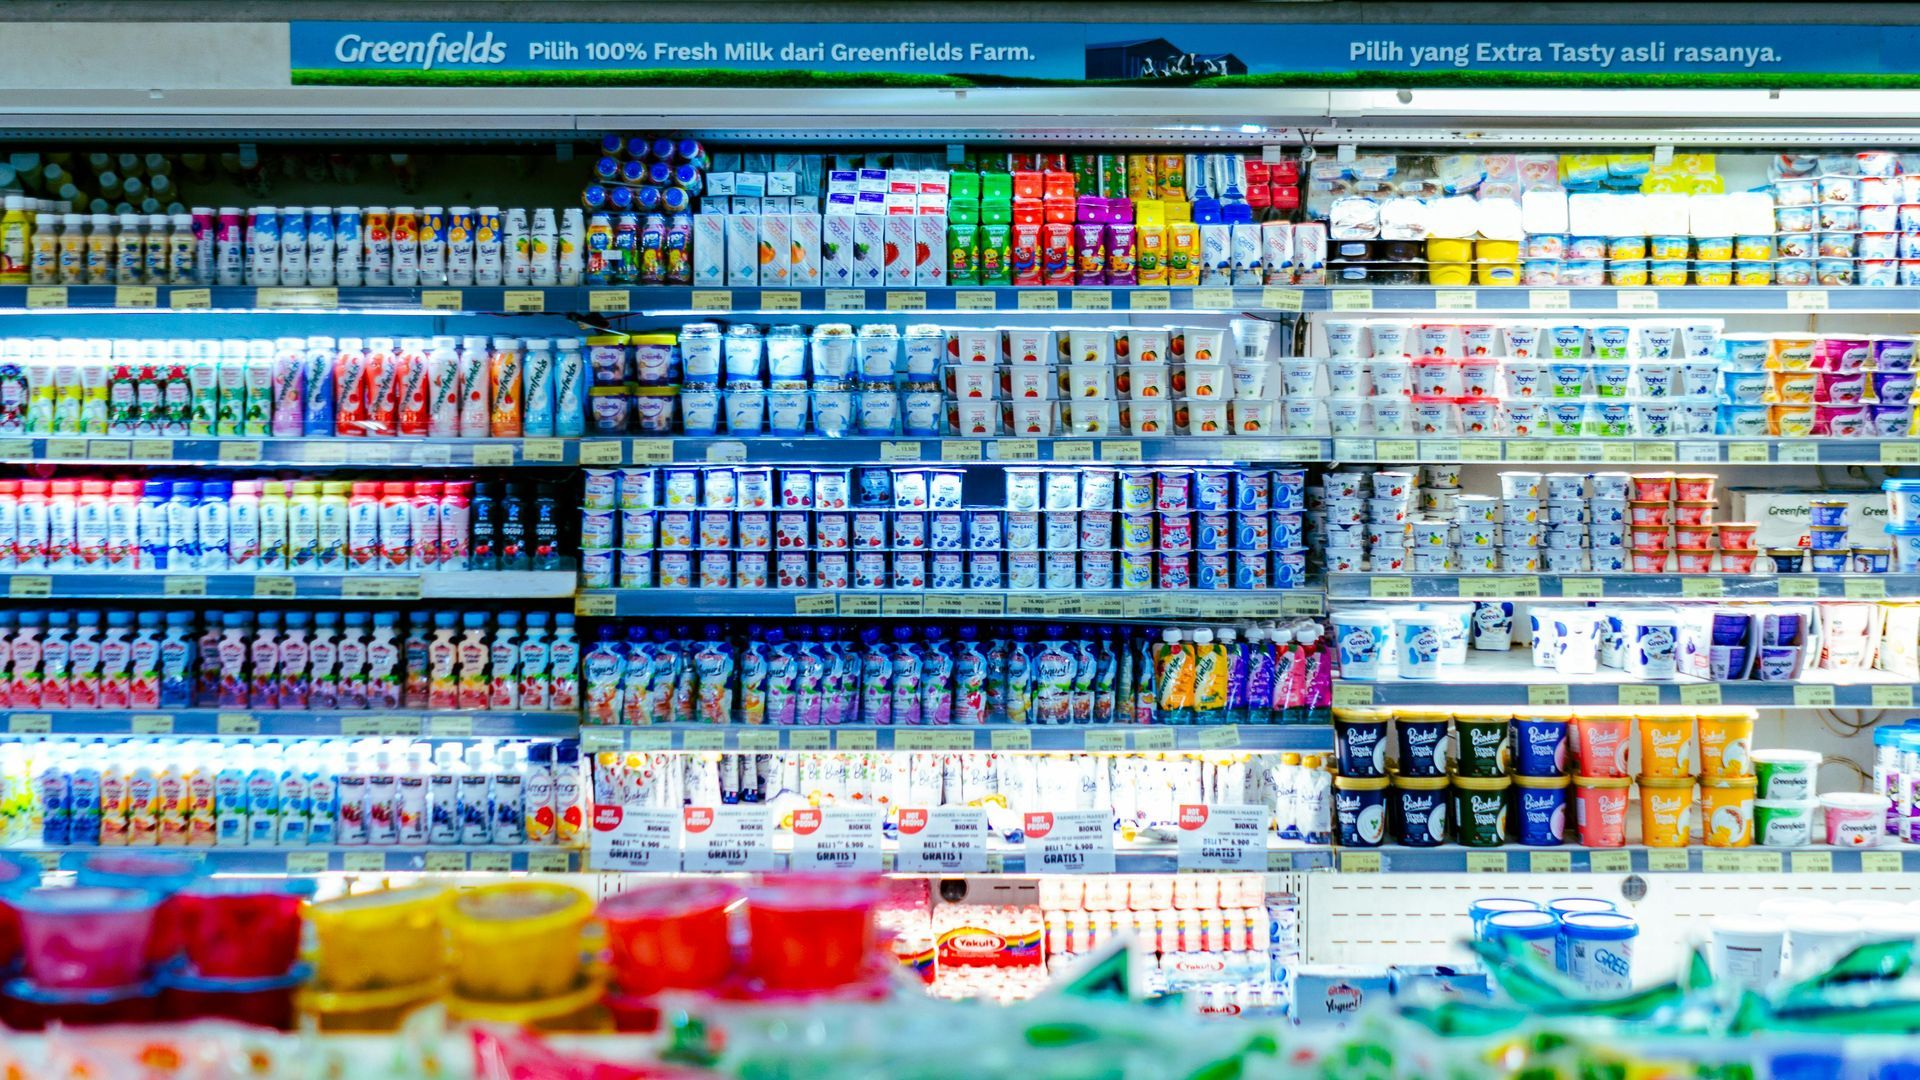
Fake news is all the rage these days, but personally, I’ve been waiting years for fake products to become more a focus of conversation. The fake products to which I refer are the ones that manufacturers and sales representatives market as “compostable” but in reality contain noncompostable plastic polymers.


In her 2016 blog article Death of Composting, Ayr Muir, founder and CEO of Clover Food Lab, a restaurant group in Boston, admonished composter Save that Stuff for no longer accepting compostable products. A longtime hauler of food scraps and compostable foodservice items, Save that Stuff had revised its policy to exclude compostable serviceware, to-go boxes, compostable cups, waxed or regular cardboard, and other paper products. In her blog, Muir wrote that her restaurants have been using all compostable products since 2010.

Other haulers adopted similar policies as several compost facilities in the Boston area announced they would only accept food scraps and would no longer accept compostable products. Institutions including the Massachusetts Institute of Technology (MIT), as well as businesses around the Boston area, were impacted.


Accepting just food scraps can make the composting process easier, as compostable products break down more slowly than food scraps. More importantly, however, post-consumer food scrap collection, especially when combined with paper and compostable foodservice items, is frequently more contaminated with non-biodegradable materials. Sometimes this occurs because “compostable” products are not fully compostable. It also occurs when food service workers, or customers busing their own plates, place plastics and other contaminants into post-consumer materials destined for a compost operation.


There are challenges to effectively diverting postconsumer food scraps and compostable products. But contamination can be successfully addressed through education. The experience of many compost operations has proven that working with haulers and customers can result in a clean stream of food scraps and certified compostable products.


However, there is no excuse for selling fake compostable products. And there’s a lot of harm done when those fake products are diverted to the organics stream. Compost operators are unknowingly processing items which do not fully degrade, which leads directly to the situation that restaurant owner Muir decried: many operations now refuse to accept compostable products because of the threat of contamination.


Meanwhile, consumers are told that these misleading products are compostable.


In 2002, standards for compostable products were established. These standards—ASTM D6400 and ASTM D6868 –establish specifications and tests that scientifically prove a material will biodegrade within a specific time frame, while leaving no persistent synthetic residues. 


To guarantee that designated products are truly compostable, the Biodegradable Products Institute (BPI) adopted a certification program. Member companies whose finished products are certified as meeting ASTM D6400 and/or ASTM D6868 can use the Compostable Logo to provide assurance of compostability or biodegradability.


The program ensures credibility and recognition for products that meet the ASTM D6400 and/or D6868 standards, so consumers, composters and regulators know that products will biodegrade as expected. The logo is designed to be placed on the actual product as well on as packaging materials and sales literature.


Despite these and other regulatory efforts, a confusing array of so-called “compostable” bags and other products, complete with “greenwashing” labels – degradable, decomposable, biodegradable, etc.—continue to be marketed. Some products employ such misleading terms as “eco” or “bio.” The use of the color green for bags is yet another tactic used to market fake products.


Thankfully, two states and at least one municipality have taken on a leadership role in addressing the issue. In 2012, California mandated that products with the label “compostable” meet ASTM standards. Then, in 2013, the law extended the restriction to all plastic products, including containers, bags, straws, lids, and utensils; in fact, any consumer product and any kind of packaging claiming to be compostable have to meet ASTM standards.


Under California’s law, products labeled “compostable” or “marine degradable” must meet the applicable standard, specifically:

  • ASTM D6400 for Compostable Plastics;
  • ASTM D7081 for Non-Floating Biodegradable Plastics in the Marine Environment;
  • ASTM D6868 for Biodegradable Plastics Used as Coatings on Paper and Other Compostable Substrates.

In 2017, Maryland adopted House Bill 1349, which requires products sold in the state and labeled as compostable to meet specific biodegradability standards. Starting in October 2018, plastic products labeled as compostable cannot be sold in the State unless they meet ASTM standards and the labeling guides in the Federal Trade Commission’s (FTC) Green Guides.


A 2011 Seattle ordinance bans single-use and biodegradable carryout bags. The ordinance was subsequently revised to address contamination from plastic bags in compost. The revised ordinance requires certain compostable bags to be labeled and tinted green. The purpose of the legislation was to reduce contamination of the City’s compost (food and yard waste) stream caused by customer misidentification and misunderstanding of which bags are compostable and which are not.


The legislation prohibits use of green or brown-tinted, non-compostable plastic bags for products such as vegetables, or for use as carryout bags. The ordinance also adds a definition of “compostable” to the code and requires that compostable bags be labeled as compostable.


Certified compostable products have a vital role in helping us to divert food scraps and compostable foodservice items from the waste stream. But until more is done to stop these fake compostable products, confusion and misunderstanding among institutions, commercial food scrap generators, haulers and composters are likely to continue. Without a more concerted effort to stop greenwashing, the organics industry will continue to face hurdles in capturing food scraps and organics from the waste stream.


By Athena Lee Bradley (with editorial input from Robert Kropp)

Share Post
By Arlene Karidis | Waste360 September 14, 2026
A new report on glass recycling in the Northeast shows that while a few front-running states have unlocked high recovery rates, there is plenty of room for the rest of the region to grow. To replicate the top achievements and scale up, the region must invest heavily in collection systems, processing infrastructure, and end-market development, according to the Northeast Recycling Council (NERC) study. A new report on glass recycling in the Northeast shows that while a few front-running states have unlocked high recovery rates, there is plenty of room for the rest of the region to grow. To replicate the top achievements and scale up, the region must invest heavily in collection systems, processing infrastructure, and end-market development, according to the Northeast Recycling Council (NERC) study. Read on to discover which states are leading the pack, where they excel, which regions are lagging, and what key industry and government insiders say about this evolving landscape. Some key findings: Vermont and Connecticut recycled the most glass containers relative to total waste generated. Connecticut led the region in per capita glass collection. New York State collected the greatest total tonnage of glass containers for recycling. Five Northeast states operate deposit return systems that include glass beverage containers. All Northeast states offer residential curbside and/or drop-off recycling programs. Vermont and Connecticut's standout glass container recovery rates are about 79.9% and 77.0%, respectively, with a common denominator being that they both operate deposit return systems (DRS) for these containers. They join a larger group whose recycling success is largely attributed to DRS programs. The Glass Packaging Institute reports that these states recover up to triple the glass captured in commingled streams, yielding more clean cullet for new containers than can be used. New York ranks as the top glass recycler with over 281,000 tons annually, followed by New Jersey at about 197,000 tons. With a population of nearly 8.6 million, New York City is the state’s largest municipality by far and plays a heavy-lifting role in driving up those statewide recovery numbers. Joshua Goodman, deputy commissioner, NYC Department of Sanitation (DSNY), says the key to healthy citywide participation has been keeping recycling simple and universal. “We pick up from every residence in the city – high-rise, low-rise, and single-family homes – and no one has to guess whether a particular piece of glass is recyclable – we take it all,” Goodman says. Building on residential success, DSNY is exploring targeting glass from construction waste next, a key strategy outlined in the draft 2026 Solid Waste Management Plan. While every Northeast state offers curbside and/or drop-off glass collection, their systems vary widely. They range from the DRS schemes like in Vermont and Connecticut to source-separated drop-off programs and, in some Pennsylvania communities, source-separated curbside collection. These system differences, along with reporting differences, complicate cross-state performance comparisons, underscoring the need for better data consistency and transparency, the authors say. To address these issues, NERC convenes a Glass Committee—a diverse group of stakeholders—regulators, municipalities, and glass processors among others—who help member states in standardizing tracking practices. “By engaging in projects through our [glass] committee, states can find paths to implement new programs or means of data collection,” says Megan Schulz-Fontes, executive director, Northeast Recycling Council. The organization is focusing on multiple areas with ambitions to strengthen the system. “Right now, we're working on developing resources and tools to support actors across the value chain in removing inefficient redundancies in collection and processing, developing a cleaner stream of recycled glass for long-term economic benefits, and identifying existing or emerging end markets for specific supply streams,” Schulz-Fontes says. New England holds the greatest promise for growth. Between municipal collections and bottle bills, the region generates massive volumes of recyclable glass. “We have made great strides in alternative end markets such as glass pozzolan [a sustainable replacement for cement in concrete]. “But what’s missing is dedicated processing facilities that clean and sort glass to achieve the necessary quality for new bottles. Historically, New England had these facilities. But, today, curbside glass often must be hauled hundreds of miles out of state just to reach a beneficiation plant,” Schulz-Fontes says, adding that re-establishing New England’s processing capacity will be a key lever to scaling glass recycling, regionwide. The idea is to eliminate long-distance transport costs, slash emissions, and keep the full lifecycle of bottle recycling local. Housatonic Resources Recovery Authority (HRRA) is working to take its Connecticut-based corner of New England further. The HRRA runs a regional glass-separation recycling program across 14 municipalities, serving roughly 265,000 residents. Since the initiative's 2019 launch, the authority has collected and sent over 2,000 tons of source-separated glass on for processing. Jennifer A. Heaton-Jones, executive director, Housatonic Resources Recovery Authority, points to another program plus. The operation has improved the quality of the whole mixed recycling stream by reducing glass contamination in paper, cardboard, and other recyclables. This helps increase the value of recyclable commodities and supports a more efficient recycling system overall, she says. Leadership credits the program's success largely to transparency and resident education. “We focused on helping residents understand what happens to glass when it is placed in a mixed recycling bin and why separating it creates better environmental and economic outcomes. “Once they learned that much of the glass collected through mixed recycling was not being recycled back into new bottles and jars due to contamination issues, they were very willing to change their behavior,” Heaton-Jones observes. The partnership with local glass recyclers helps—it is giving residents visible proof that their glass is being transformed to new products. “When people know their efforts make a measurable difference, participation follows,” she says. Casella processes approximately 100,000 tons of glass annually across Connecticut, Maine, Massachusetts, New Hampshire, New York, Pennsylvania, and Vermont. According to Jeff Weld, the company’s vice president of communications, they have access to several viable end markets. He cites bottle-to-bottle recycling, fiberglass manufacturing, processed glass aggregate, and additives for concrete and other construction applications. Building a diverse network of regional outlets has been a key strategy. Because glass is heavy and carries a lower commodity value, regional processing is essential to cutting transportation distances and keeping processing costs manageable, Weld says. That’s what’s most needed, he advises—more local and regional outlets to make logistics more efficient while improving the long-term economics and resiliency of glass recycling. In the broader picture, economic factors favor glass recycling, according to market research platform Worldmetric’s data . Nationwide, U.S. recycling costs $35 to $50 per ton while landfilling costs $20 to $30, according to Worldmetric’s 2026 report. The authors cite a national selling price of $80 to $100 per ton and claim recycled content saves manufacturers $10 to $15 per ton. But regional realities paint a more nuanced picture. NERC’s market value figures for the Northeast show the region faces a tighter squeeze, other than for clear glass, likely attributed to the referenced processing challenges compounded by single-stream contamination. Just the same, opportunities exist across the region. But closing the loop will require a dual approach: building robust, updated infrastructure and aggressively driving the long-term market demand to sustain it. Read on Waste360.
By Sophie Leone August 25, 2026
Circular Action Alliance (CAA) was founded in 2022 and is a U.S. Producer Responsibility Organization (PRO). As a PRO they are dedicated to the implementation of effective Extended Producer Responsibility laws for paper and packaging. CAA operates as the single PRO in California, Colorado, Maryland, Minnesota, Oregon and Washington. Additionally, they are the only organization that is approved to implement U.S. EPR laws for paper and packaging. CAA's dedicated and important work is built off a comprehensive list of strategic operating principles. These principles include delivering cost effective services, supporting and incentivizing innovation in packaging design, supporting responsible end markets, and enhancing the collection of covered materials. CAA not only works with the producers but with the greater industry as well, providing free webinars, public resources, state updates, and more. "We're excited to join NERC and contribute to its long legacy of regional collaboration," said Bridget Anderson, Director of Emerging States at Circular Action Alliance. "As we implement EPR programs in multiple states, organizations like NERC help us better understand regional nuances and trends in the recycling system." NERC is excited to welcome the Circular Action Alliance. As a fellow non-profit, we look forward to supporting their growing impact and the important work they do with EPR. For more information on CAA visit.
By Access Newswire August 20, 2026
We are more than halfway through 2026, making this a good moment to reflect on what stands out from all the recent change in the sustainability landscape. We review news about sustainability all week, every week, but we also work closely with clients in a range of industries who are dealing with the daily work of environmental protection, social advancement, governance integrity, and - perhaps the most complicated aspect - how to talk about it all. So, while the loudest headlines have been about retreat in regulations, target-setting, hiring, and corporate reporting, there is another truth worth telling: what companies do has not changed much. The stories in this issue of Sustainability Highlights explore the two sides of this contrast. In Forbes, Anjali Chaudhry assembles the numbers behind "greenhushing." EcoVadis found 87% of U.S. companies maintained or increased sustainability investment in 2025 and only 7% cut, while 31% of executives invested more and said less. Forbes investigated whether the silence paid off, and found it was not the safe harbor companies expected: 98% of businesses in a 2026 procurement survey had lost contract opportunities for not sharing sustainability credentials. Standard-setters may have a sense of why this is. In Eco-Business, Global Reporting Initiative chief executive Robin Hodess says GRI has seen no decline in reporting numbers, with four in five of the largest global companies still using GRI Standards. Offering a clue about why reporting has stayed strong this year, she makes a business case for robust disclosures: "I've never met an investor who wants less information." The size and tenor of the comment file received by the SEC over the past few months bears out Hodess' view. As Responsible Investor reports, Vanguard - the world's second-largest asset manager - is the largest investor to oppose scrapping the climate rules, telling the Commission there is value in standardized, comparable disclosure of material risks - climate among them. TIAA and Nuveen argued for a simplified rule rather than none, warning of a "mosaic of state-specific requirements." If sustainability were receding, we wouldn't be hearing about more hours for lawyers. Corporate Disclosures picked up Side by Side , our new research with Ropes & Gray, and led with a finding that surprised us too: 39% of the sustainability professionals surveyed now report into the legal department, against 17% reporting to the CEO. According to 87% of them, and 84% of their legal counterparts, interaction has increased because of regulation. California's climate laws and the CSRD each were named by 75% of our respondents as the most pressing reason for greater collaboration between legal and sustainability teams. Majorities in both groups expected legal's role to grow; not a single respondent expected it to shrink. Capital is moving the same way. ESG Dive reports U.S. sustainable funds drew roughly $3 billion in the second quarter - the first positive quarter since 2022, ending 14 straight quarters of outflows and lifting assets to a record $398 billion. But the developments also show signs of caution: the money went to passive strategies, active funds shed $3.6 billion, and 22 funds closed against three launches. Other timely news delves into AI's role in sustainability matters. Inside Climate News reports on applications increasing oil and gas output, MIT Sloan cites the climate costs and benefits of AI tools, and we found two takes on whether data centers and clean power can share a grid. These stories paint the backdrop for our new issue brief on Responsible AI Due Diligence , which is a guide to the OECD's first guidance for the AI value chain. On circularity, the EU's Packaging and Packaging Waste Regulation is in force this month, including PFAS limits on food-contact packaging. The Northeast Recycling Council has mapped policies on producer stewardship in 11 U.S. states, offering useful context for our resource paper on the EU's PPWR and our EPR support work. Also inside: $20 billion in climate grants unblocked on appeal, and the world's largest carbon removal plant due online by year's end. This is just the introduction of G&A's Sustainability Highlights newsletter this week. Click here to view the full issue. Read on Access Newswire .